Invicta Motors · MG
MG company-car tax explained
Understand P11D, 2026/27 benefit percentages and two transparent electric-MG examples.

At a glance
- Electric MGs: zero-emission company cars use a 4% benefit percentage in 2026/27.
- Worked examples: base MG4 Urban and MGS5 EV calculations show the assumptions—not a personalised tax quote.
- For hybrids: confirm the exact certified figures and applicable HMRC treatment with payroll.
The monthly payment is not the company-car tax
If an MG is available for private use as a company car, your tax is normally based on its taxable list-price value, the appropriate benefit-in-kind percentage and your income-tax rate. It is not simply the lease payment or the discounted price your employer pays.
For 2026/27, from 6 April 2026 to 5 April 2027, a zero-emission car has a 4% company-car benefit percentage. That makes MG’s electric range worth considering for a business-car shortlist, alongside its suitability for your journeys.
Two electric MG illustrations
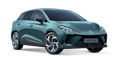
MG4 EV Urban Comfort Standard Range
- Current starting OTR list price
- £23,495
- Calculated illustration value
- £23,430
- 2026/27 benefit percentage
- 4%
- Tax at a 20% marginal rate
- £187.44/year · £15.62/month
- Tax at a 40% marginal rate
- £374.88/year · £31.24/month
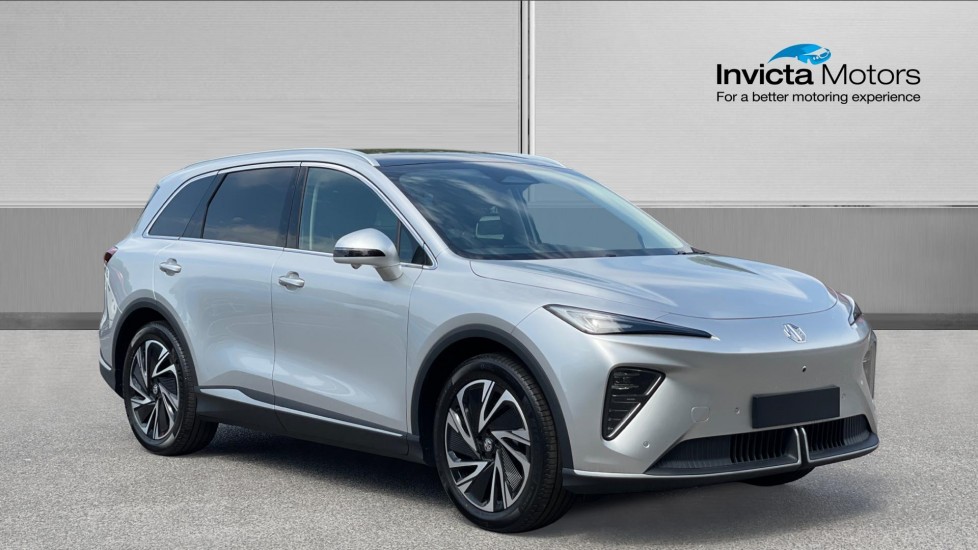
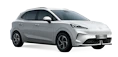
MGS5 EV SE Standard Range
- Current starting OTR list price
- £28,995
- Calculated illustration value
- £28,930
- 2026/27 benefit percentage
- 4%
- Tax at a 20% marginal rate
- £231.44/year · £19.29/month
- Tax at a 40% marginal rate
- £462.88/year · £38.57/month
How these examples are calculated: the starting OTR list prices are from MG’s current UK configurator. We deduct the £55 first-registration fee and £10 first-year zero-emission VED to illustrate the taxable list-price value, following MG’s P11D definition. These are calculated base-car illustrations, not quoted MG P11D schedule entries.
Each assumes standard paint, no chargeable accessories, full-year private availability and no employee contribution. Tax = illustration value × 4% × the stated marginal income-tax rate; monthly amounts are annual tax divided by 12. Confirm the actual P11D value and payroll treatment on your fleet quotation.
What belongs in the P11D value?
MG describes P11D value as the recommended retail price including VAT and delivery, but excluding first-registration fee and road tax. Chargeable accessories can increase the value used in the calculation.
A dealer discount, manufacturer contribution or electric-car incentive should not automatically be deducted from the taxable list-price value. Keep the fleet quotation’s cash price and P11D fields separate.
The examples use 20% and 40% marginal income-tax rates, not universal employee rates. Scottish income-tax bands, higher rates and your personal circumstances can change the amount you pay.


Plug-in hybrids need two extra checks
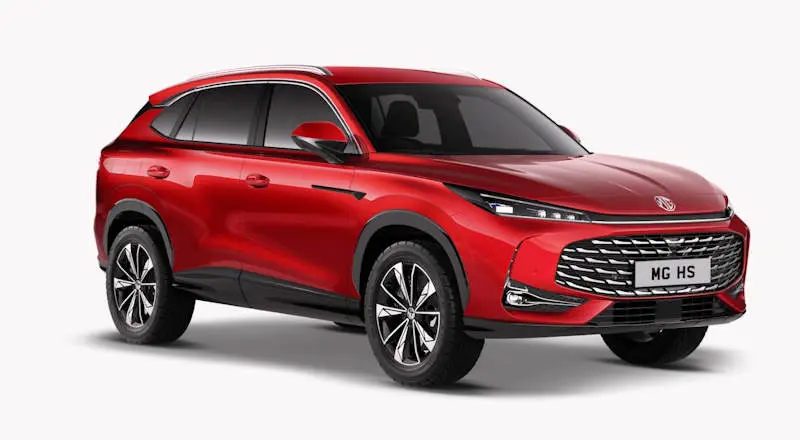
For a plug-in MG such as HS, both the tax-relevant CO₂ figure and certified electric range matter. In 2026/27, a car in the 1–50g/km band with 70–129 miles of certified electric range has a 7% benefit percentage; 40–69 miles uses 10%.
MG quotes up to 75 miles WLTP electric range for the current HS Plug-in Hybrid, but use the certified value and tax treatment for the exact derivative—not “up to” range as proof of every car’s band.
HMRC also has a temporary easement for qualifying newer-test-regime PHEVs. Subject to its conditions, a nominal 1g/km is used for company-car benefit calculations. Ask payroll to check that rule rather than assigning a band solely from a newer registration document’s higher CO₂ figure.
Full hybrid does not mean the EV tax rate
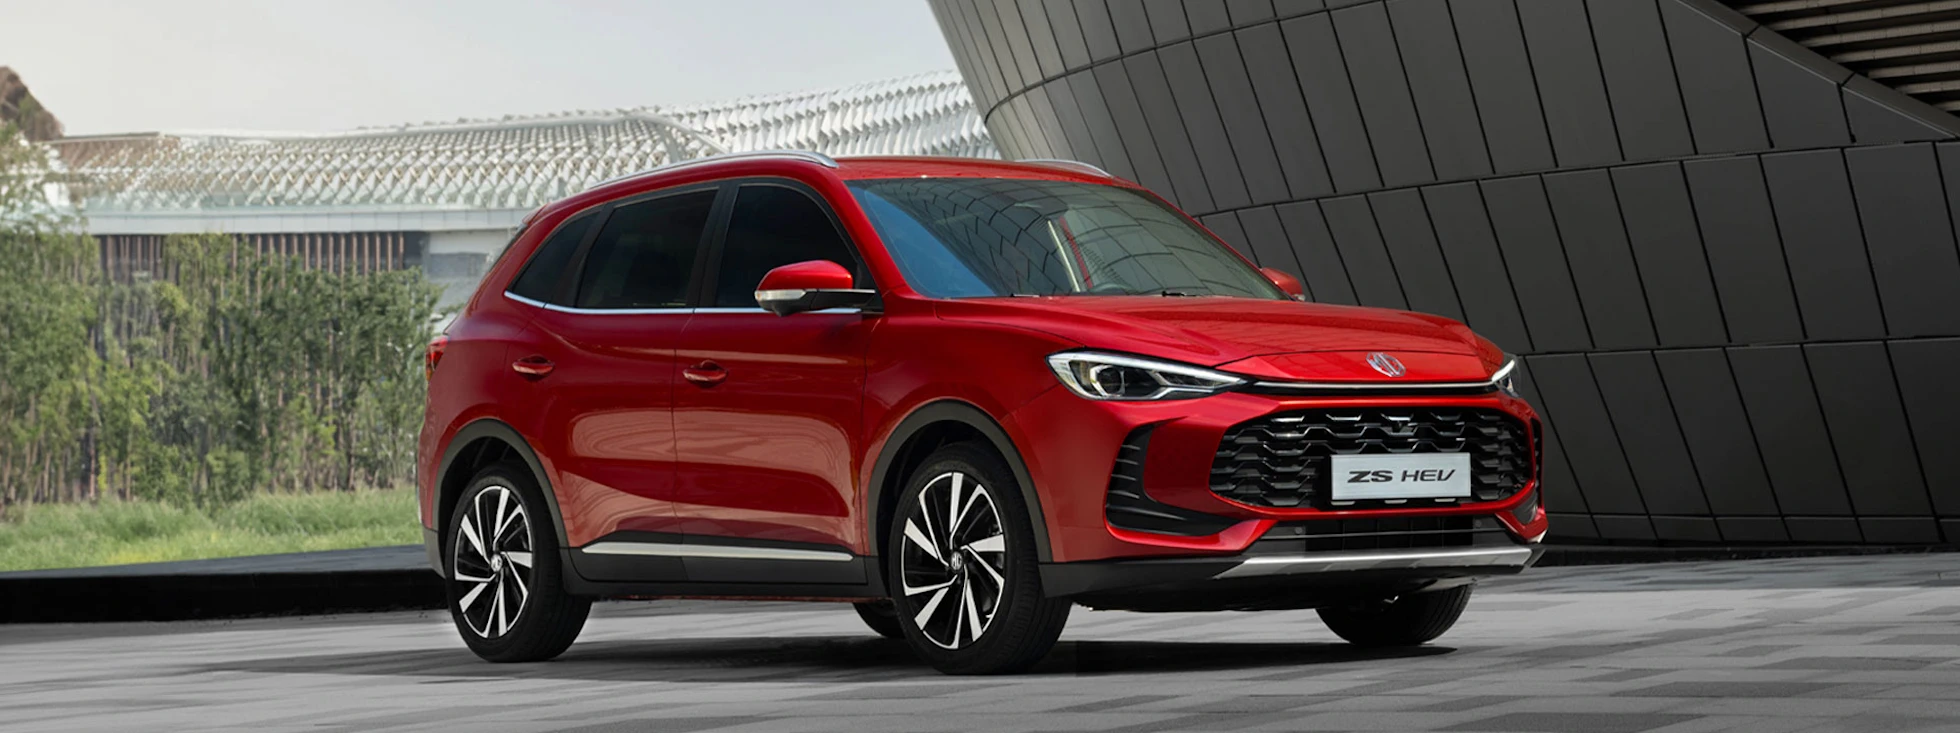
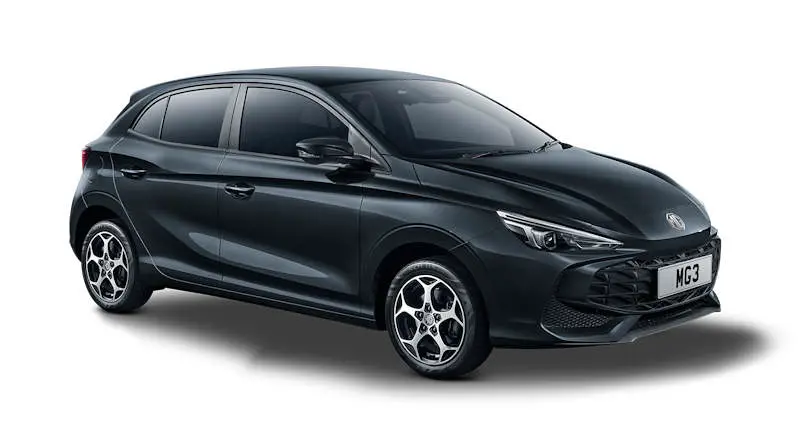
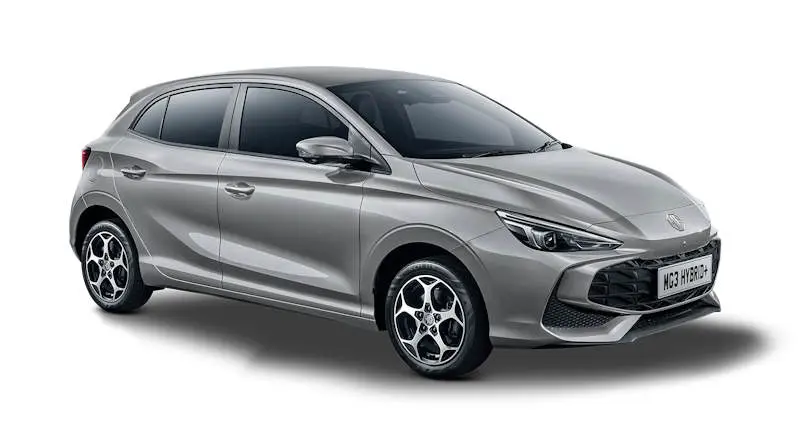
MG3 Hybrid+ and ZS Hybrid+ do not plug in and are not zero-emission cars. Their company-car percentage depends on the applicable CO₂ figure and tax-year rules; the Hybrid+ badge alone does not give them the 4% electric-car rate.
Before choosing, request the exact derivative, standard and optional equipment, P11D value, certified CO₂ and electric range where relevant. Then ask your employer or payroll team to confirm the resulting benefit and tax.
Private-fuel benefits, employee contributions and periods when the vehicle is unavailable need separate treatment. The simple examples above do not include them. Your payroll team or tax adviser should confirm the figure before you commit.

Your questions answered
Is company-car tax based on my lease payment?
What rate applies to a zero-emission MG in 2026/27?
Are the example values official MG P11D table entries?
Does an MG discount reduce P11D by the same amount?
Do all MG hybrids qualify for 7%?
Are private fuel and employee contributions included?
Build your MG business-car shortlist
Ask for the exact model specification and a quotation showing the P11D value, then confirm the tax treatment with your employer.
Sources: HMRC 2026/27 rates; Government company-car guidance; MG P11D definition; MG current configurator; Vehicle tax rates; First-registration fee; HMRC PHEV easement; MG current HS brochure.
UK information checked 14 October 2026. Prices, offers and specifications may change.